3 Personal Injury Law Myths Debunked by an Injury Attorney
Jared Bingham • October 21, 2026

October 21, 2026

After an accident, injured individuals often face uncertainty about their legal rights, financial responsibilities, and options for pursuing compensation. Misinformation about personal injury claims can make an already difficult situation more stressful, potentially causing victims to overlook opportunities to recover damages or accept settlements that do not adequately address their losses.


Understanding how personal injury law works can help you make informed decisions about your next steps. An experienced injury attorney can clarify misconceptions, explain the claims process, and help you evaluate your options. The following three myths address important considerations for those wondering how to proceed after an accident.


Myth 1: You Can Handle Any Personal Injury Claim Without Legal Representation

Understanding the Complexity of Personal Injury Law

Some accident victims believe they can manage their claims independently because the circumstances seem straightforward. However, personal injury cases can become complicated when liability is disputed, injuries are serious, or insurance companies challenge the requested compensation. These claims involve legal standards, documentation requirements, and negotiation strategies that may be unfamiliar to someone without legal experience.


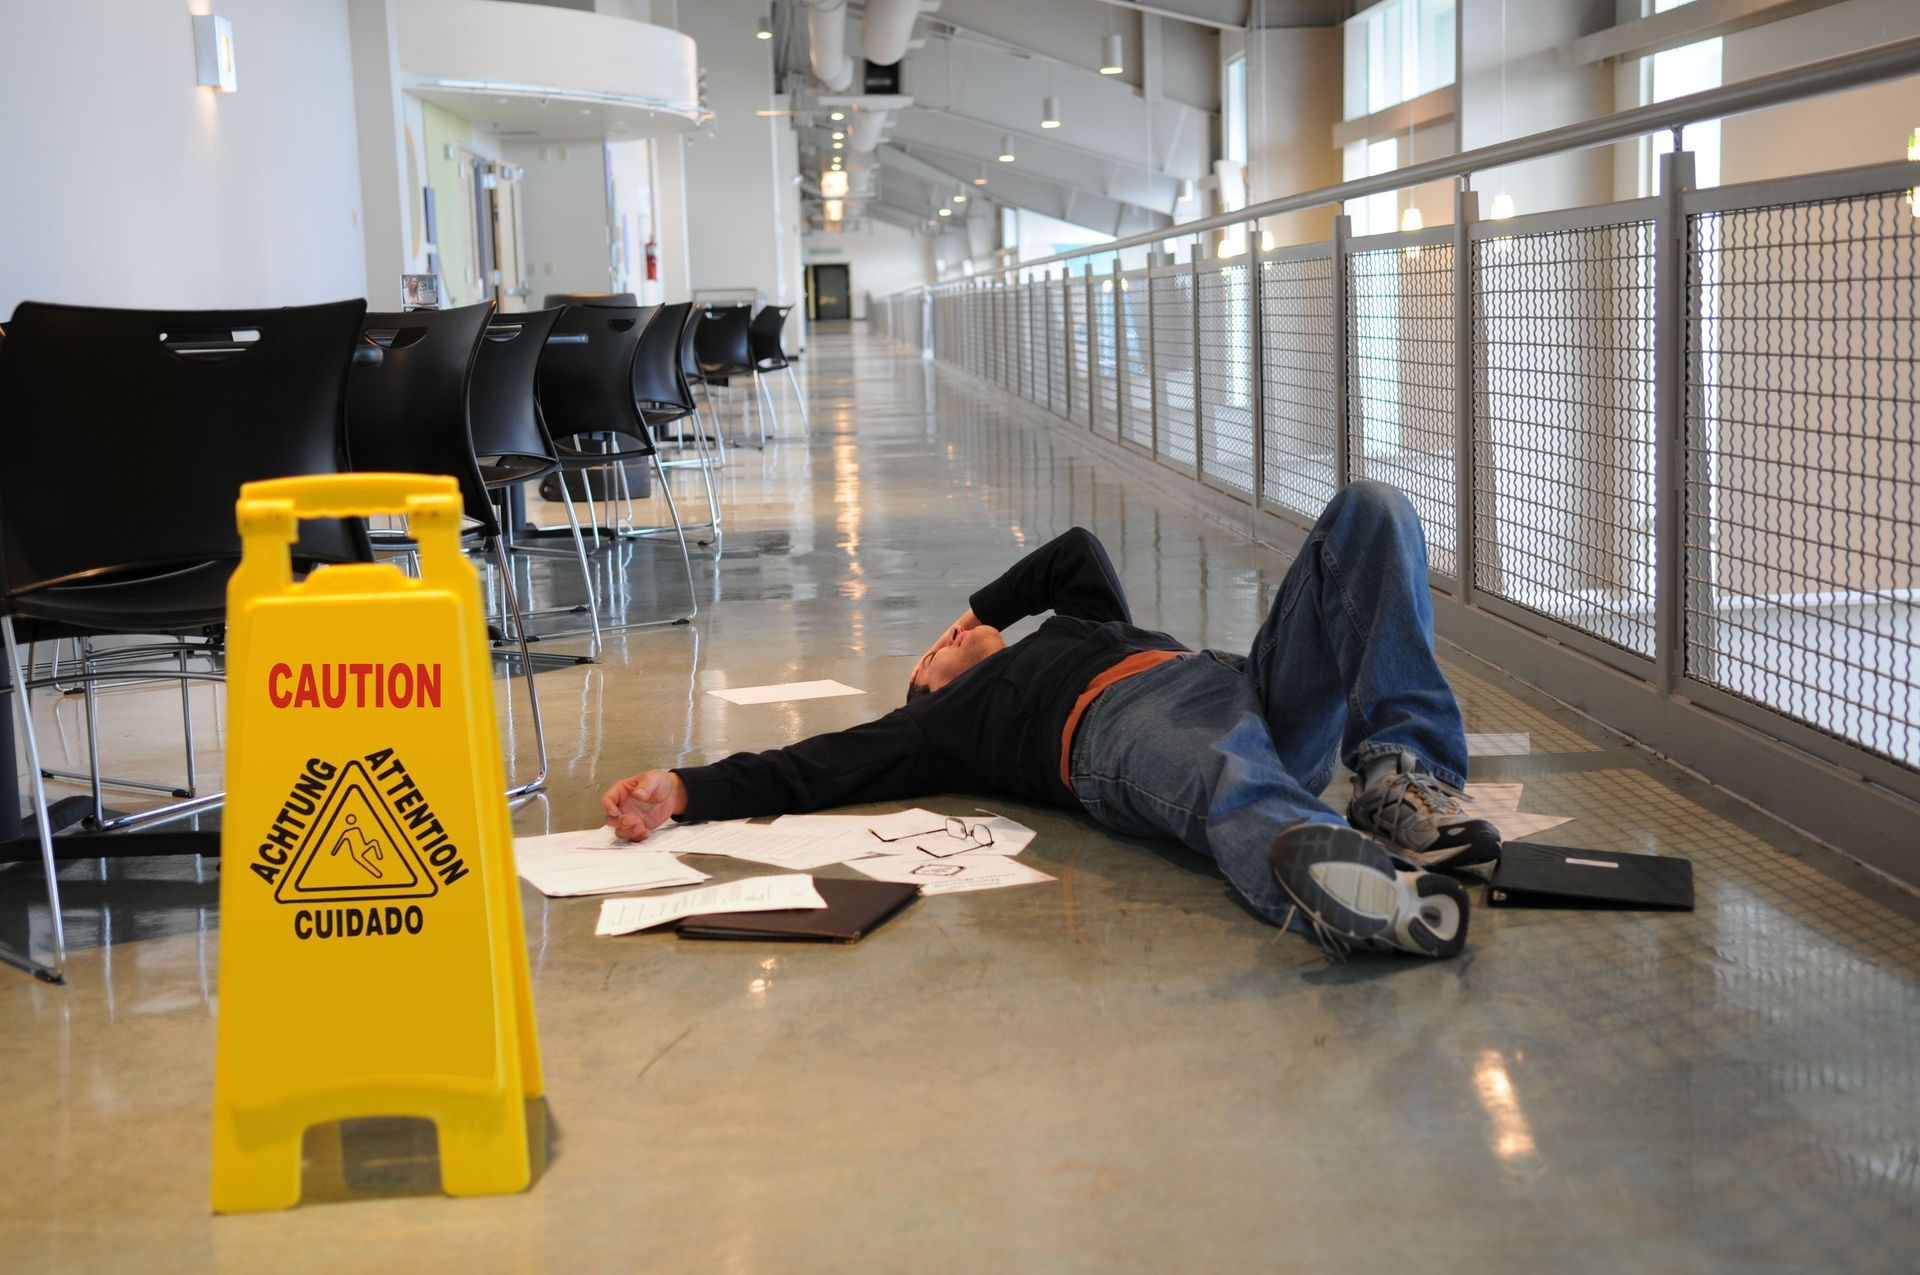
For example, a car accident might initially appear to involve one responsible driver. However, road conditions, vehicle maintenance, witness statements, or the actions of multiple parties could affect liability. Slip and fall incidents can present similar challenges when property owners dispute whether they knew about a hazardous condition. An injury attorney can investigate the circumstances, identify potentially responsible parties, and determine what evidence may support your claim.


Recognizing the Risks of Handling Insurance Negotiations Alone

Insurance companies have established procedures for investigating claims and evaluating potential payouts. Adjusters may request statements, review medical records, and examine evidence to determine whether an insurer should accept responsibility. Without understanding the implications of these requests, injured individuals may unintentionally weaken their claims or overlook important documentation.


A settlement offer may seem appealing when medical bills are accumulating and missed work is reducing household income. However, accepting an offer without considering future treatment costs, ongoing physical limitations, and other losses could leave you responsible for expenses that arise later. Once a settlement is finalized, pursuing additional compensation for the same injuries may be difficult or impossible.


Knowing When Professional Guidance Can Help

Even claims that appear straightforward may benefit from an initial legal evaluation. A consultation allows you to discuss the accident, review available documentation, and understand potential obstacles before making major decisions. You can also ask questions about liability, compensation, deadlines, and the responsibilities involved in pursuing a claim.


Many law firms offer free consultations and work on a contingency fee basis, meaning legal fees depend on obtaining a recovery under the terms of the agreement. This arrangement can make legal guidance more accessible to people facing unexpected expenses. Seeking advice early may also help preserve evidence and prevent avoidable mistakes as you pursue compensation.


Myth 2: Personal Injury Claims Always Take Years to Resolve

Understanding What Determines a Claim's Timeline

Another common misconception is that every personal injury case involves years of litigation before an injured person receives compensation. In reality, the timeline depends on factors such as injury severity, liability disputes, evidence availability, and the willingness of the parties to negotiate. Some claims settle through insurance negotiations, while others require extensive investigation or courtroom proceedings.


According to Gitnux, approximately 75% of personal injury cases take 12 to 24 months to resolve after filing. Individual cases may conclude sooner or take longer depending on their circumstances. The filing date is also only one milestone, as gathering evidence, receiving medical treatment, and negotiating with insurers may begin beforehand.


Learning Why Some Cases Take Longer Than Others

Disputes over responsibility can extend the process considerably. An insurer might argue that its policyholder did not cause the accident or that another party shares responsibility. The parties may need additional evidence, expert opinions, or witness testimony before they can evaluate the claim. Cases involving multiple defendants or complicated accident circumstances may require even more investigation.


The amount of compensation at stake can also influence negotiations. Serious injuries involving long-term care or permanent impairment may require detailed assessments of future expenses and financial consequences. If negotiations fail, filing a lawsuit can introduce additional stages, including discovery, depositions, motions, and potentially a trial. An injury attorney can explain which factors are affecting your case and what steps may come next.


Avoiding Decisions Based Solely on Speed

Wanting a quick resolution is understandable, particularly when medical expenses and lost income create financial pressure. However, the fastest settlement is not necessarily the most appropriate one. An offer made before the extent of an injury is understood may fail to account for continuing treatment, reduced work capacity, or other losses that develop over time.


Instead of focusing exclusively on speed, consider whether a proposed settlement reflects the documented and reasonably anticipated effects of the accident. Your legal representative can review medical information, wage records, and other evidence to assess whether the offer addresses your major losses. You should also understand the release terms and whether accepting payment will end your right to pursue further damages.


Myth 3: You Cannot Recover Compensation if You Share Some Responsibility

Understanding How Shared Fault Can Affect a Claim

Some injured people assume that making a mistake before an accident automatically prevents them from receiving compensation. This belief can discourage victims from seeking legal advice, even when another person or organization may have contributed to their injuries. In many jurisdictions, shared responsibility does not automatically eliminate the possibility of recovery. The applicable rules depend on the laws governing the claim and the circumstances of the incident.


For example, a driver involved in a collision might have been traveling above the speed limit when another motorist made an unsafe turn. Similarly, someone injured on another person's property might have overlooked a warning sign while the property owner failed to address a dangerous condition. An injury attorney can review available evidence to assess how responsibility may be allocated under the applicable law.


Examining Comparative and Contributory Negligence Rules

Different jurisdictions apply different standards when an injured person shares responsibility for an accident. Under comparative negligence systems, compensation may be reduced according to the claimant's assigned share of fault, subject to the jurisdiction's specific rules. Some jurisdictions use modified comparative negligence, which can restrict recovery when the injured person's percentage of responsibility reaches a particular threshold.


Other jurisdictions follow contributory negligence principles, under which a finding that the claimant contributed to the injury may significantly restrict or bar recovery, subject to applicable exceptions. These distinctions matter because the same accident could produce different legal outcomes depending on where the claim is brought. An injury attorney familiar with the applicable jurisdiction can explain how these rules may affect your claim.


Protecting Your Rights After an Accident

If you suspect that you contributed to an accident, avoid assuming you have no options before obtaining legal guidance. Preserve relevant records, keep copies of medical bills, document missed work, and retain photographs or other evidence related to the incident when available. Be careful when providing statements about fault before you understand the circumstances and potential legal consequences.


You should also pay attention to filing deadlines. Personal injury claims are generally subject to statutes of limitation, and certain claims may have shorter deadlines or additional notice requirements. Missing an applicable deadline can jeopardize your ability to pursue compensation, regardless of the underlying merits of your case. A qualified injury attorney can evaluate the evidence, explain your rights, and communicate with insurance companies on your behalf.


Personal injury myths can create unnecessary uncertainty when injured individuals need clear information and practical guidance. Understanding your legal options, allowing sufficient time to evaluate damages, and recognizing how shared fault may affect recovery can help you make informed decisions after an accident. If you have questions about your rights or potential compensation, consider contacting JDB Law and scheduling a consultation with an experienced personal injury attorney.

injury attorney
September 21, 2026
From gathering visual evidence to calculating future medical bills, see how a dedicated injury attorney guides you through a slip and fall claim.
personal injury attorney
September 18, 2026
Struggling to secure fair compensation after a wreck? Discover the proven ways a personal injury attorney navigates collision cases to protect your rights.
Police car roof with flashing blue lights at night
July 28, 2026
KSL News reported a tragic crash that occurred on Thursday, August 1, 2024, in Duchesne County, Utah. The news article reports that the victim and her friends were hit by a suspected DUI driver. The video of this crash scene shows the horrific damage to the vehicles. Our thoughts and prayers go out to the victims and their families, and we wish them all a speedy recovery. See, https://ksltv.com/668518/teen-faces-a-long-recovery-after-she-was-hit-by-a-suspected-dui-driver/ While a DUI crash may seem straightforward when it comes to liability, there are often other issues that come up for the victim and their loved ones in dealing with the aftermath of such a terrible crash. Here are just a few things that victims in cases like these should keep in mind: Auto Insurance Coverage : In Utah the State requires drivers to have at least $3,000.00 in Personal Injury Protection (PIP) coverage. This coverage is known as no-fault coverage since no matter who caused the accident, your own PIP coverage must be used to pay your initial medical bills. Additionally, the State of Utah only requires a minimum of $25,000.00 of bodily injury coverage (note that this amount is going up to $30,000.00 in 2025). That means that drivers can lawfully operate their vehicles with this minimum amount available to cover any bodily injury caused by their negligent driving (including driving under the influence of drugs or alcohol). As you can imagine, in a case like this one reported by KSL, the victims will have medical bills that far exceed this $25,000.00 minimum in coverage. Here is how this plays out for the injury victims: 1. PIP - the victim's PIP coverage pays medical bills up to their $3,000.00 limit (or higher if they have higher PIP coverage). 2. Bodily Injury (BI) Coverage - because the at-fault driver's BI insurance does not pay medical bills until the victim has completed all treatment, any medical bills beyond PIP will need to be submitted to the victim's own health insurance provider. This will ensure that the bills are paid and not sent to collections while the victim is still in treatment and recovering (which can take months or longer). Once the victim has finished treatment, all medical bills can be sent to the at-fault driver's BI insurance carrier for a lump sum settlement. But here is where we see the biggest problem in these types of cases: if the at-fault driver's BI coverage is only $25,000.00 (or even $50,000.00), and that amount is not enough to cover the victim's medical bills, what options do they have? Underinsured Motorist (UIM) Coverage: Accidents are unpredictable and can happen to anyone, at any time. While having insurance is a legal requirement and provides a safety net, it’s crucial to understand that not all insurance policies are created equal. One essential component of a robust insurance policy is underinsured motorist (UIM) coverage. Here’s why having good underinsured motorist coverage is important: 1. Protection Against Inadequate Insurance Despite mandatory insurance laws, many drivers carry only the minimum required liability insurance, which may not be sufficient to cover the costs of a serious accident. If you’re involved in an accident with an underinsured driver, their policy limits might be too low to cover your medical bills, property damage, and other expenses. Example: If the at-fault driver has a liability limit of $25,000, but your medical expenses alone amount to $50,000, you would be left with significant out-of-pocket costs. Good UIM coverage would help bridge this gap. 2. Comprehensive Medical Coverage Medical expenses following an accident can be exorbitant, encompassing emergency care, hospital stays, surgeries, rehabilitation, and ongoing treatment. Underinsured motorist coverage can help ensure that you receive the necessary medical care without facing financial hardship. Example: Your UIM coverage can help cover the cost of specialized treatments, physical therapy, or long-term care that might not be fully covered by the at-fault driver’s insurance. 3. Compensation for Lost Wages A severe accident can lead to time off work, either temporarily or permanently. Lost wages can compound the financial strain caused by medical bills and other expenses. Underinsured motorist coverage can provide compensation for lost income, helping to alleviate the financial burden during your recovery period. Example: If you’re unable to work for several months due to your injuries, your UIM coverage can help replace lost income, allowing you to focus on your recovery without worrying about financial instability. 4. Coverage for Pain and Suffering In addition to tangible costs like medical bills and lost wages, accidents can cause significant pain and suffering. This includes physical pain, emotional distress, and a reduced quality of life. Underinsured motorist coverage can provide compensation for these non-economic damages, offering some relief for the intangible impacts of an accident. Example: If you experience chronic pain or emotional trauma following an accident, UIM coverage can help compensate for these enduring challenges. 5. Protection for Passengers Your underinsured motorist coverage doesn’t just protect you—it also protects your passengers. If friends or family members are injured while riding in your vehicle, your UIM coverage can help cover their medical expenses and other associated costs. Example: If your child or a friend is injured in an accident caused by an underinsured driver, your UIM policy can help cover their medical treatment and recovery expenses. 6. Legal Peace of Mind Accidents involving underinsured drivers often lead to complex legal battles to recover adequate compensation. Having robust UIM coverage can simplify the process and reduce the need for protracted legal disputes. This coverage can expedite the claims process, allowing you to receive compensation more quickly. Example: Rather than pursuing a lengthy and costly lawsuit against an underinsured driver, your UIM coverage can provide immediate financial support, helping you avoid additional stress and legal expenses. 7. Financial Security Ultimately, good underinsured motorist coverage provides financial security in the face of the unexpected. It ensures that you and your loved ones are protected, even if the at-fault driver’s insurance falls short. This peace of mind is invaluable, knowing that you have a safety net in place. Example: In the event of a serious accident, your UIM coverage can prevent you from depleting your savings or going into debt to cover medical bills and other costs. Accidents involving underinsured drivers are more common than you might think, and the financial implications can be devastating. Having good underinsured motorist coverage is a critical aspect of a comprehensive insurance policy, offering protection and peace of mind when you need it most. It ensures that you’re not left financially vulnerable due to someone else’s inadequate insurance. At JDB Law PLLC, we advocate for responsible coverage and are here to help you understand and maximize your insurance benefits. If you have questions about your coverage or need assistance after an accident, contact us today for expert guidance and support.
Show More →